
 iscover
‘Moving feast’ of CGT reform riddled with uncertainty
BusinessThe ATO has an uphill battle administering the new CGT legislation as it has started releasing guidance on “the biggest CGT event in Australian history”, according to a tax adviser.
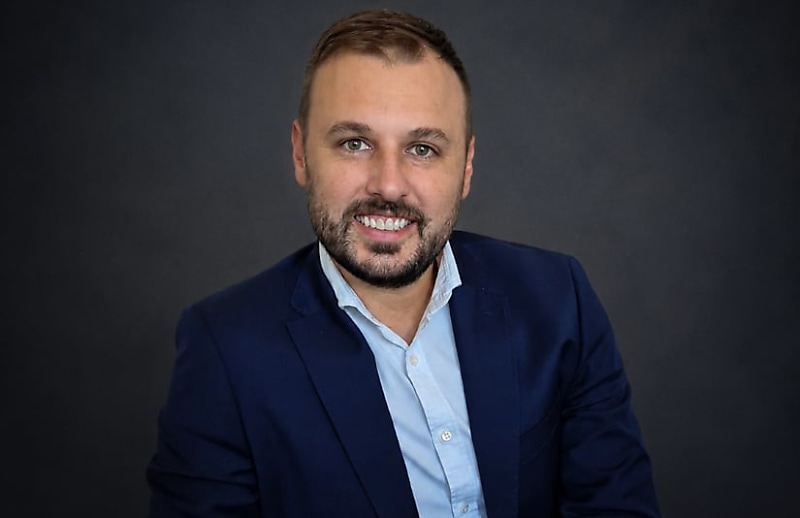
Hilltop Tax Advisory principal Gavin Quayle noted that the ATO has started releasing its much-awaited guidance on the deemed sale and re-acquisition on 1 July 2027, as indexation is due to replace the CGT discount from that date.
In its guidance, the ATO said transitional arrangements may apply to a CGT asset that a taxpayer holds on 1 July 2027 and acquired before that date.
The law will apply as if the taxpayer has disposed of the asset immediately before 1 July 2027 and reacquired it on 1 July 2027.
“In this case, in calculating your gain or loss, you may need to determine the market value of your CGT asset immediately before 1 July 2027,” the ATO said.
The ATO also noted that taxpayers have the choice to use the alternative apportionment method suggested in the legislation. It said any gain or loss is deferred.
“You only need to report it when you later dispose of the asset or another CGT event occurs in respect of that asset,” the ATO said.
Furthermore, the ATO said it will provide further guidance on the apportionment method once the government has developed and enacted it.
In a LinkedIn post, Quayle said the ATO has been “dealt a tricky hand” because Treasury has left it to administer a “half-baked” legislation that the government pushed through parliament without any meaningful consultation.
Speaking with Accountants Daily, Quayle outlined several challenges the ATO is faced with in administering the new laws, namely, lack of certainty of law.
“The current law that’s on the books has already been subject to revision and is subject to ongoing revision. It is also subject to the minister making a determination for critical elements on that law,” Quayle said.
“The ATO has effectively got this moving feast of law that it’s supposed to be administering, which is unusual in these circumstances. Typically, we’d have a robust and lengthy consultation process that explores all views. Then you’ve got a design that the government lands on. By the time it becomes law, you’ve got a level of certainty of law.”
The second pain point, Quayle continued, is the sheer complexity of the law, with the ATO left to interpret it, train their staff, and administer it.
Valuation agitation
In addition, Quayle highlighted the need for certainty around valuations, and said he expects many taxpayers to consider a formal valuation after 1 July 2027 as it could produce a better tax outcome than the government’s proposed apportionment method, particularly where most of the growth occurred before 1 July 2027.
“That’s where the greatest amount of uncertainty is and where compliance costs for taxpayers are going to be the greatest,” Quayle said.
“You’ve got the ATO’s market valuation guidelines, which are esoteric and designed for the adviser end of the market rather than your standard mum and dad taxpayers with some unlisted shares. Now, everyone’s got to get a valuation.”
Quayle pointed out that it could be difficult to value a business using the apportionment method because that may not offer a true reflection of the growth of that business, in which case obtaining a valuation could work in the business’ favour.
“That can be complex for a business. How do you value goodwill, an internally-generated asset? That's a big problem. It also depends on at the time of the future sale, is it back ended growth or is it front loaded growth? Where is the value?” he said.
Noting that a valuation from a specialist could cost between $3,000 and $5,000, which many businesses may not be able to afford, Quayle said he hopes the ATO will offer a series of safe harbour approaches and methodologies that provide businesses a broad ballpark valuation, and one which the ATO would accept as an administrative workaround.
Quayle said he is currently educating his clients on the mechanics of the shift to indexation and discussing if they would be required to undertake a valuation or use the “fallback” apportionment method.
“Because there are two options, my recommendation to my clients is to at least consider the valuation so that they've then got the optionality,” he said.
 Want to see more stories from trusted news sources?
Make Accountants Daily a preferred news source on Google.
