


 iscover
Taxpayer loses appeal after blaming tax agent for FTL
TaxA taxpayer has lost his appeal in the Federal Court of Australia after the Commissioner of Taxation determined that he was liable for penalty assessments after a failure to lodge personal income tax returns in 2017.
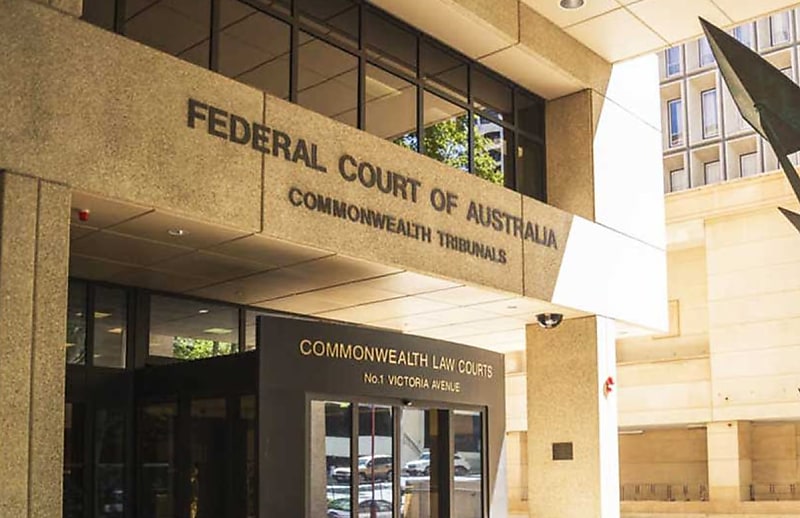
The Federal Court of Australia judge Sarah C Derrington has rejected a taxpayer’s application for appeal against penalty assessments after the judge determined that the taxpayer failed to provide medical evidence to prove that his medical conditions prevented him from lodging his tax returns in 2017.
In the matter, Adam Bruce Watson sought a review of the Administrative Appeals Tribunal’s rejection of his objection to a default and penalty assessment issued in respect of the 2017 income year in a matter against the Commissioner of Taxation.
“Mr Watson submitted that the reason he was contesting the disallowance of his objection to the default and penalty assessment in the Tribunal was because he had ‘done nothing wrong’,” Judge Derrington found.
Watson gave evidence that he did not lodge his 2017 income year tax return because of his bookkeeper, who failed to lodge the relevant return despite email instructions to, when she went on a “frolic of her own”.
“Mr Watson claims, however, that the content of the email was different from that which he had directed Ms Preketes to send and that he was oblivious to that fact because of his illiteracy,” the court heard.
“Mr Watson contends that the Tribunal’s acceptance of Ms Preketes’ evidence has caused him a great injustice and that the Tribunal would not have accepted her evidence had it properly considered Mr Watson’s inability to read or write.”
Watson asserted that the tribunal failed to consider his medical conditions in the previous decision, which included diabetes, mental health challenges and “other difficult personal circumstances”.
He claimed that he would “suffer substantial injustice if leave [was] not granted because he will, in effect, be left unable to challenge the Tribunal’s refusal to reinstate his review proceedings and consequently have no way to challenge the underlying tax assessment which he maintains is incorrect”, the court found.
The court noted that despite these claims, the tribunal did not receive any evidence from his treating specialists as to “whether [his] medical conditions were capable of making [him] prone to outbursts that affected [his] judgment…”.
Thus, the court determined that these claims were not enough to satisfy the requirement that the proceeding be reinstated.
“The reason the proceeding was ultimately dismissed by the Tribunal was because Mr Watson was unable to produce the necessary evidence,” the court said.
For these reasons, the judge dismissed the appeal application on the basis that Watson failed to discharge the onus of proof on his penalties, ordering him to pay the commissioner’s costs.
The case citation: Watson v Commissioner of Taxation (No 2) [2026] FCA 1341 (14 September 2026).
 Want to see more stories from trusted news sources?
Make Accountants Daily a preferred news source on Google.
