


 iscover
‘Blameworthy act’: taxpayer’s objection to $6m in penalties for evading $16m in income tax scrapped
TaxThe Federal Court of Australia has dismissed a taxpayer’s summary judgment application seeking an objection to an almost $6 million administrative penalty for evasion, where he omitted an over $16 million loan from his returns.
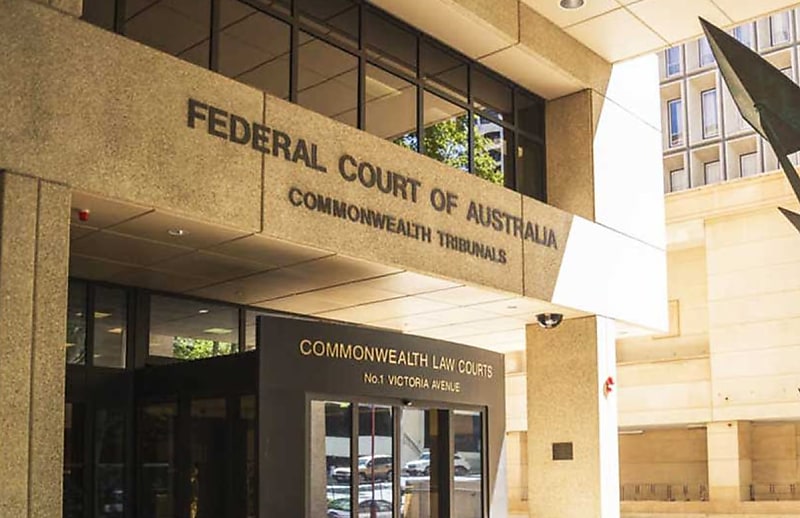
Federal Court of Australia Justice Melissa Anne Perry has dismissed taxpayer Sergio Peter Laureti’s summary judgment application, on the grounds that he failed to prove that the 75 per cent shortfall penalty, amounting to $5,735,998.09 in administrative penalties for alleged tax evasion, was excessive.
For his income tax returns for the financial years ending 30 June 2001 to 30 June 2011 inclusive, Laureti declared a total taxable income of $695,429, while he was a director and shareholder of Laureti Management Services Pty Ltd (LMS).
The commissioner conducted an audit of Laureti’s tax affairs on 25 May 2012 and, in its 5 July 2022 audit position paper, determined he had evaded tax following a review of his returns by the National Fraud or Evasion Panel, which was carried out a month prior.
In the audit, the commissioner uncovered that Laureti held a loan account with LMS of $16,126,798, which he omitted from his total taxable income of $695,429 in his returns during this period.
“It is the Commissioner's view that by failing to declare the amounts in your loan account as income, you made false representations, avoided tax, and committed a blameworthy act or omission,” the commissioner said in its audit position paper.
“The Commissioner considers that you have satisfied the threshold of evasion and therefore the Commissioner may amend your income tax assessments at any time.”
Following this discovery, the commissioner determined that Laureti was liable to an administrative penalty of 75 per cent of the tax shortfall – on the basis that he committed an intentional disregard of taxation law – which, along with the Medicare levy, totalled $5,735,998.09.
On 20 December 2022, Laureti made an objection application to the 11 assessments of administrative penalty, which failed. On 28 April 2026, Laureti sought a summary judgment against the commissioner to appeal the dismissal of his objection.
“The applicant’s submission on its face seeks to circumvent the burden of proof on him to establish that the shortfall amounts are either excessive or do not arise wholly or partly from an intentional disregard of a taxation law,” the court heard.
Justice Perry determined that this is a “clear case where summary judgment is not appropriate” on the basis of Laureti’s failure to establish excessiveness of the 75 per cent shortfall.
In her 10 August 2026 decision, Perry dismissed Laureti’s summary application against the commissioner and provided the latter the opportunity to amend its appeal statement to specify the taxation law that Laureti “intentionally disregarded” in his furnished tax returns.
The case citation: Laureti v Commissioner of Taxation [2026] FCA 1086.
Editor's note: This story has been updated since publication.
 Want to see more stories from trusted news sources?
Make Accountants Daily a preferred news source on Google.
