
 iscover
Auditor registration hurdles for small firm accountants impede supply
BusinessThe restrictive requirements for accountants at smaller firms to become a registered auditor risk exacerbating the supply shortage of auditors, according to one practice principal.
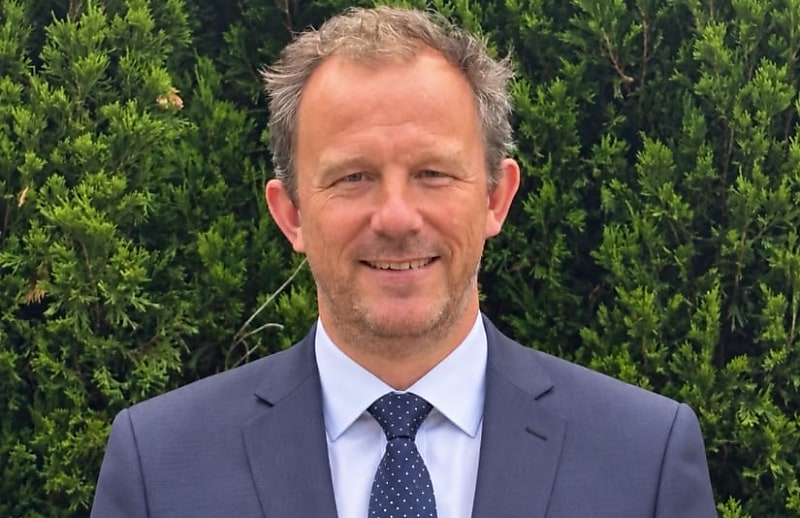
Kirk Davis Accounting principal and aspiring company auditor Kirk Davis aired his grievances over the arduous process accountants at smaller firms face to become ASIC-registered company auditors (RCA) compared to those at the large accounting firms.
This is despite auditors at the large firms like KPMG being engulfed in scandals relating to alleged audit misconduct and allegations of the mishandling of confidential client information, he pointed out.
“I think ASIC is creating a monopoly where only the large firms can register. But at the same time, some of the large firms are in trouble for alleged unethical behaviour,” Davis said.
The barriers that are preventing small firm accountants and sole practitioners from becoming ASIC-registered RCAs are exacerbating the short supply of auditors and affecting the quality of the accounting profession, Davis told Accountants Daily.
The Australian Securities and Investments Commission’s (ASIC) registered auditor dataset figures showed that over the past 20 years to 2025, the number of RCAs plummeted from 6,173 to 3,073. As at 5 June 2026, that number dwindled further to 2,998, while as at 20 October 2026, this figure dropped again to 2,952 RCAs.
The number of RCAs has dropped by 58 per cent since 2003, when there were 7,025 company auditors in total.
Long road to becoming RCA
Davis recounted that he has faced significant difficulties in his attempt to become an ASIC-registered RCA since July 2024. He completed 3,000 hours of auditing work and was supervised by an RCA for over 750 hours.
Davis and his supervisor provided ASIC with a statutory declaration and other signed documents, including a table of the hours and listings of the audit duties performed.
While Davis did not supervise formal staff himself as a sole practitioner, he created a collaborative supervisory arrangement with an RCA where he would manage the audits, meet the clients, prepare audit engagements, review risks, and prepare the audit manual.
Upon completion of the audit process, his supervisor reviews all his work papers, attends meetings with Davis, and signs off on the audit engagement.
The Corporations Regulations 2001 states that an auditor must have undertaken at least 3,000 hours’ worth of work in auditing under the direction of an RCA during the five years immediately before the date of the application. This must include appraising the operations of companies and forming opinions on various matters, and spending at least 750 hours supervising audits of companies.
However, according to Davis, ASIC applied Regulatory Guide 180 on auditor registration, which states that, as a minimum, a competency standard should require evidence of the competent performance of tasks involving the ability to supervise staff and manage an audit.
Davis contended that as a sole practitioner, he is the audit manager while his supervisor and RCA is the audit partner, but he has not employed any junior staff.
“ASIC’s view is that I can’t register because I haven’t supervised other people,” Davis told Accountants Daily.
“I don’t argue with the requirements stipulated in RG180. But there is an alternative way stated in the Corporations Regulations, which does not require supervision of staff. It refers to the supervision of audit of companies.”
Davis lodged a freedom of information (FOI) request over his own documents as he wanted to view ASIC’s correspondence regarding his case, which he received from ASIC on 30 September 2026.
In a letter to ASIC chair Sarah Court dated 3 October 2026 and viewed by Accountants Daily, Davis attached an extract from the documents he received through his FOI request.
The extract, which was also viewed by Accountants Daily, contains an email from an ASIC senior inspector to former senior executive leader, licensing Peng Lee.
In the email, the senior inspector said: “Mr Davis is correct that the Corps Act does not mention the supervision of staff but refers to supervising audits of companies.”
Davis said in his letter to Court: “Clearly ASIC became aware that its approach to assessing the application for registration as a company auditor was not in accordance with the Corporations Act and Regulations, yet it continued to apply that approach.”
Davis told Accountants Daily that ASIC did not reverse its decision to reject his RCA application despite the statement by the senior inspector in his email to Lee.
“ASIC just said it can’t grant me the auditor registration. I believe they refused my application on an incorrect basis,” he said.
“I think ASIC is not applying the Corporations Regulations correctly. Even though they admit that I’m correct and I don’t need to supervise staff as per that email, ASIC is still saying they’ve got no discretion and they can’t register me, so it makes no sense.”
Davis said he has written to the ASIC chair around seven times over the last two years. While ASIC acknowledges receipt of his letters, he said his application has not progressed.
Obstacles remain for small firm accountants
He said that he and other small firm accountants like him are excluded from registration unless he recruits staff and supervises them, which he does not intend to do.
“They’re blocking out most small businesses,” he said.
When asked if he believes ASIC makes it easier to become an auditor at the large accounting firms, Davis said: “They do without a doubt.”
“Under ASIC’s RG 180 model, the idea is you complete 3,000 hours at a large firm and you supervise junior staff once you become a manager,” he said.
“That’s the model they want. They want you to follow RG 180, which says you must supervise staff. But they also say that RG 180 applies to the alternative method, which is incorrect because the alternative method was presumably designed to help small businesses qualify, which is me.”
Withdrawal of application ‘under protest’
Accountants Daily contacted ASIC for comment and sent several questions regarding Davis’ case, but it did not respond to those questions.
Instead, a spokesman noted that Davis applied for review of his application for registration to the Administrative Review Tribunal, withdrew his RCA application in August 2025, and has not lodged a further application to date.
Davis said he withdrew his application “expressly under protest” after ASIC issued three notices under section 30 of the ASIC Act 2001 to his supervisor in August 2025, requiring his firm to produce certain books and give specified information to ASIC to help it assess Davis’ application.
The penalty for failing to comply with a notice without reasonable excuse is $79,200, or two years’ imprisonment, or both, the notices said.
Davis appeared at his third ART hearing last week and said the tribunal would reach a decision in the next few months.
 Want to see more stories from trusted news sources?
Make Accountants Daily a preferred news source on Google.
